DHURSAN CONSTRUCTION

General

a quaint beach house in the hamptons style

Hamptons Style: The Ultimate Guide!

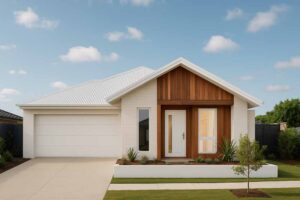
The allure of American coastal luxury has found a permanent home in Australia, transforming ordinary houses into sophisticated retreats that capture the essence of elite beachside living. Hamptons style represents more than just an interior design trend – it’s a lifestyle philosophy that celebrates relaxed elegance, natural beauty, and timeless sophistication. From the weatherboard facades that grace our coastal suburbs to the carefully curated interiors that balance comfort with glamour, this distinctive style continues to captivate Australian homeowners seeking that perfect blend of casual luxury. What makes Hamptons style so enduring is its remarkable ability to adapt to different climates, lifestyles, and personal tastes while maintaining its core identity. Whether you’re building a new home or renovating an existing property, understanding the fundamental elements of this coveted aesthetic will help you create spaces that feel both aspirational and authentically welcoming. This comprehensive guide will walk you through every aspect of Hamptons style, from architectural details to interior styling secrets. What is Hamptons Style? Hamptons style is a sophisticated interpretation of traditional American colonial architecture, adapted for seaside living with expansive porches, large windows, and materials that could withstand coastal conditions while maintaining an air of understated luxury. It originated in the exclusive summer communities of Long Island’s East End, where America’s elite established grand coastal retreats during the late 19th and early 20th centuries. The core philosophy of Hamptons style centres on effortless sophistication – creating spaces that appear naturally beautiful without obvious artifice. This aesthetic philosophy emphasises quality over quantity, choosing fewer pieces of superior craftsmanship rather than filling spaces with numerous decorative items. The style celebrates the interplay between indoor and outdoor living, recognising that the most beautiful homes seamlessly connect inhabitants with their natural surroundings. What resonates so deeply with Australian homeowners is how Hamptons style aligns with our outdoor lifestyle and appreciation for coastal living. The emphasis on natural light, breezy textures, and relaxed entertainment spaces mirrors the quintessential Australian approach to home design, making it feel both aspirational and authentically suitable for our climate and culture. Hamptons Style House Exteriors The exterior of a Hamptons style house immediately communicates its design philosophy through distinctive architectural elements that have become synonymous with coastal luxury. Characteristic features include steep gabled rooflines that create dramatic visual interest while providing practical advantages for weather protection. These rooflines often incorporate dormer windows that add both architectural detail and additional interior light. Material choices play a crucial role in achieving authentic Hamptons aesthetics. Weatherboard cladding, painted in crisp whites or soft coastal tones, forms the foundation of most Hamptons exteriors. This traditional American siding creates the horizontal lines that define the style while providing practical weather resistance. Cedar shingles offer an alternative texture that ages beautifully, developing a silvered patina that enhances the coastal aesthetic over time. Window and door treatments deserve special attention in Hamptons design. Generous window proportions flood interiors with natural light while creating the sense of transparency between indoor and outdoor spaces. Traditional timber window frames, painted white or in complementary coastal colours, provide the classic detailing that distinguishes Hamptons style from more contemporary designs. Shutters, whether functional or decorative, add authenticity and visual interest while reinforcing the American coastal heritage. Landscaping considerations for Hamptons style houses emphasise informal elegance that complements rather than competes with architectural elements. Native coastal plants, manicured lawns, and established trees create the relaxed sophistication associated with established coastal communities. Pathways using natural materials like stone or timber connect different outdoor areas while maintaining the organic feel essential to authentic Hamptons design. Hamptons Style House Interior Design Hamptons style interior design revolves around creating spaces that feel both sophisticated and completely comfortable, achieving that coveted “forever holiday” atmosphere that makes everyday living feel special. The foundation of any successful Hamptons interior lies in maximising natural light and creating seamless connections between rooms and outdoor spaces. Essential design principles include generous room proportions that accommodate both large gatherings and intimate family moments. Open-plan living areas work particularly well in Hamptons style homes, allowing natural light to flow throughout spaces while creating the relaxed, unstructured feeling that defines the aesthetic. However, defined zones within these open areas prevent the spaces from feeling cavernous or lacking intimacy. Colour palettes in Hamptons style house interior designs traditionally centre on crisp whites and soft neutrals, creating a fresh backdrop that reflects light and maintains the breezy coastal feeling. Classic Hamptons blue – ranging from soft powder blues to deeper navy tones – provides the signature accent colour that connects interiors to coastal surroundings. These base colours allow for flexibility in furniture and accessory choices while maintaining the timeless appeal that makes Hamptons style enduringly popular. Furniture selection emphasises quality pieces with classic proportions and natural materials. Oversized sofas upholstered in linen or cotton provide comfortable gathering spots, while timber furniture pieces in oak, pine, or painted finishes add warmth and texture. The key lies in choosing pieces that appear effortlessly elegant rather than obviously expensive, creating spaces that feel collected over time rather than purchased all at once. What is the Australian Version of the Hamptons? Australian interpretation of Hamptons style has evolved into what designers often call “Modern Hamptons,” adapting traditional American elements to suit our unique climate, lifestyle, and aesthetic preferences. This localised version maintains the sophisticated coastal essence while incorporating contemporary elements that reflect Australian indoor-outdoor living preferences. The Australian version often features more relaxed interpretations of traditional Hamptons rules, particularly regarding colour choices and material selections. While maintaining the foundational whites and blues, Australian designers frequently incorporate warmer neutrals like soft greys, sandy beiges, and coastal greens that reflect our diverse landscape. These colour adaptations help Hamptons style feel more connected to Australian coastal environments rather than appearing as direct American replicas. Climate considerations significantly influence how Australians interpret Hamptons style. Our stronger sun and outdoor lifestyle needs result in homes with even more generous outdoor entertaining areas, larger opening windows and doors, and materials chosen for durability in harsh Australian conditions.

Read More »
What is a raked ceiling? Internal home layout.

What is a Raked Ceiling? A Builder Explains

When designing your dream home, few architectural features can transform a space as dramatically as a raked ceiling. This striking design element has gained immense popularity amongst Australian homeowners seeking to create light-filled, spacious interiors that feel both luxurious and functional. But what exactly is a raked ceiling, and why might it be the perfect addition to your home? As experienced home builders, we’ve witnessed firsthand how raked ceilings can completely redefine a living space, turning ordinary rooms into architectural showpieces. Let’s explore everything you need to know about this impressive ceiling design choice. What is a Raked Ceiling? A raked ceiling is an angled or sloped ceiling that follows the natural pitch of your roof’s trusses, rather than sitting flat like traditional ceilings. Also known as cathedral ceilings or vaulted ceilings, these architectural features create dramatic upward angles that draw the eye skyward and maximise the use of available space beneath your roofline. Unlike standard flat ceilings that create a horizontal barrier between your living space and roof cavity, raked ceilings embrace the full height potential of your home’s structure. The ceiling literally “rakes” upward at an angle, typically mirroring the slope of the roof above, creating a sense of soaring space and architectural drama. The design follows the natural lines of your home’s framework, transforming what would otherwise be unused roof space into valuable ceiling height. This creates an immediate visual impact that makes rooms feel significantly larger and more open than their actual square meterage suggests. The Benefits of Raked Ceilings Enhanced Sense of Space and Height The most immediately noticeable advantage of raked ceilings lies in their ability to create an illusion of vastness. By angling upward, these ceilings draw the eye toward the highest point of the room, making even modestly-sized spaces feel grand and expansive. Dhursan Construction recommends raked ceilings particularly for open-plan living areas or rumpus rooms where you want to enhance the feeling of spaciousness. The height and angle draw the eye upward, making the room feel much larger and airier than it actually is. This vertical expansion proves especially valuable in modern Australian homes where open-plan home designs reign supreme. The additional height creates natural zones within large spaces without requiring physical barriers, allowing for better flow and functionality. Improved Natural Light Distribution Raked ceilings excel at capturing and distributing natural light throughout your living space. The angled surfaces provide multiple planes for light to bounce off, creating a brighter, more evenly lit environment compared to flat ceiling alternatives. The increased ceiling height often allows for larger windows or additional glazing options, such as highlight windows positioned high on walls. These elevated windows capture light from different angles throughout the day, reducing reliance on artificial lighting and creating dynamic shadows that change with the sun’s movement. Superior Air Flow and Ventilation One of the most practical advantages of raked ceilings involves improved air circulation. The additional volume creates natural convection currents that help hot air rise away from living areas, particularly beneficial during Australia’s warm summer months. This enhanced air movement reduces stuffiness and creates a more comfortable interior climate. When combined with strategically placed windows or ventilation systems at the ceiling’s peak, raked ceilings can significantly improve your home’s natural cooling efficiency. Architectural Character and Visual Interest Raked ceilings serve as powerful design features that add architectural sophistication to any home. The clean lines and dramatic angles create visual interest that elevates interior spaces from ordinary to extraordinary. These striking ceiling lines provide opportunities for creative lighting design, exposed beam features, or unique architectural details that become focal points within your home. The result is a space that feels like a thoughtfully crafted custom home design. Considerations When Choosing Raked Ceilings Additional Costs and Construction Complexity Installing raked ceilings requires more materials, specialised construction techniques, and additional labour compared to standard flat ceilings. The angled framework demands precise measurements and skilled craftsmanship to achieve proper structural integrity and weatherproofing. Budget considerations should include not only initial construction costs but also potential increases in heating and cooling expenses due to the larger volume of space. However, many homeowners find these costs justified by the dramatic improvement in living quality and home value. COST RELATED CONTENT: CAN INTERNATIONAL STUDENTS BUY PROPERTY IN AUSTRALIA? Heating and Cooling Efficiency The increased ceiling height created by raked ceilings means more air volume to heat or cool, which can impact energy efficiency. Hot air naturally rises to the ceiling’s peak, potentially creating temperature stratification where the upper portions of the room become uncomfortably warm while living areas remain comfortable. Strategic planning can address these challenges through ceiling fan installation, zoned heating and cooling systems, or proper insulation techniques that minimise energy loss while maintaining comfort. Maintenance Requirements Cleaning and maintaining raked ceilings can present challenges due to their height and angled surfaces. Changing light bulbs, dusting exposed beams, or addressing any ceiling-mounted fixtures requires appropriate equipment and safety considerations. Professional maintenance may be necessary for some tasks, adding to long-term ownership costs. However, modern construction techniques and quality materials can minimise maintenance requirements while ensuring lasting performance. Design Compatibility Raked ceilings work exceptionally well with certain architectural styles, particularly contemporary, country, and transitional designs. However, they may not complement every home style, and careful consideration should be given to ensure the feature harmonises with your overall design aesthetic. The dramatic nature of raked ceilings makes them statement features that influence other design decisions throughout your home. Consider how furniture placement, window treatments, and decorative elements will work with the angled ceiling lines. Best Applications for Raked Ceilings Raked ceilings prove most effective in main living areas where families spend significant time and where the dramatic height can be fully appreciated. Open-plan kitchen, dining, and living combinations particularly benefit from the sense of grandeur and improved functionality these ceilings provide. Family rooms, great rooms, and entertainment areas also serve as excellent candidates for raked ceilings, especially when these spaces connect to outdoor living areas through large doors or windows. The combination

Read More »
What is a site plan?

A Guide to Site Plans (Tips from Homebuilding Experts)

Whether you’re embarking on your first home building project, purchasing property, or planning renovations, understanding what a site plan is becomes fundamental to your success. A site plan serves as the blueprint that bridges your vision with reality, transforming abstract ideas into tangible construction guidance. At its core, a site plan is a detailed architectural drawing that provides a bird’s-eye view of your entire property. This comprehensive document illustrates existing conditions, proposed developments, and the relationship between your future home and the surrounding environment. For Australian homeowners and home builders, site plans are not merely helpful documents—they’re legal requirements that ensure compliance with local council regulations and building codes. What Is a Site Plan? The Foundation of Your Building Project A site plan, also known as a plot plan or site layout, is a technical document that serves as a communication tool between architects, builders, council authorities, and homeowners. This ensures everyone shares the same vision for your project. A site plan serves multiple critical functions beyond simple illustration. These drawings demonstrate compliance with zoning requirements, assist in obtaining building permits, guide construction teams during the building process, and provide legal documentation of your property’s development. Essentially, a site plan functions as both a practical tool and a legal document. Modern site plans incorporate sophisticated surveying techniques and computer-aided design software, resulting in precise measurements and accurate representations. This technological advancement ensures your site plan reflects actual ground conditions and provides reliable information for construction planning. Essential Components Every Site Plan Must Include Property Boundaries and Legal Descriptions Every site plan begins with clearly defined property boundaries, marked with precise measurements and bearing information. These boundary lines establish the legal limits of your property and determine where construction can occur. Australian site plans must reference the Certificate of Title and include survey marks, ensuring absolute accuracy in property definition. Setback requirements form another crucial boundary consideration. Front, side, and rear setbacks dictate the minimum distances between your proposed structures and property lines. These measurements ensure compliance with council requirements and maintain neighbourhood character consistency. Existing Site Features and Conditions Comprehensive site analysis requires documenting all existing features on your property. This includes mature trees, existing structures, natural features like rock formations or water bodies, and topographical variations. Understanding what is a site plan means appreciating how these existing elements influence your home design and construction approach. Utility locations represent critical existing conditions that directly impact construction planning. Your site plan must accurately show the position of electricity meters, gas connections, water mains, sewer lines, and telecommunications infrastructure. This information prevents costly mistakes during excavation and ensures efficient connection of new services. Proposed Development Elements The heart of any site plan lies in its proposed development elements. Your future home’s footprint, including all structural components, appears as a scaled representation showing exact positioning relative to boundaries and existing features. This includes the main dwelling, garages, outdoor entertainment areas, and any secondary structures like sheds or studios. Landscaping elements form an integral part of modern site plans, reflecting the growing emphasis on outdoor living and environmental considerations. Proposed gardens, pathways, retaining walls, pools, and outdoor entertainment areas all require careful planning and accurate representation on your site plan. Reading and Interpreting Site Plan Symbols Understanding Scale and Measurements Site plans typically use metric scales, commonly 1:100 or 1:200 for residential properties. This means that one millimetre on the drawing represents 100 or 200 millimetres in real life. Understanding scale allows you to visualise actual distances and proportions, making it easier to assess whether your proposed development suits your needs and expectations. Dimension lines and measurement annotations provide specific distances between key elements. These measurements form the basis for construction layout and must be accurate to ensure proper building positioning and compliance with setback requirements. Decoding Standard Site Plan Symbols Site plan symbols follow Australian Standards conventions, ensuring consistency across different professionals and projects. Building outlines typically appear as bold, solid lines, while proposed structures may be shown with different line weights or patterns to distinguish them from existing elements. Landscaping symbols represent different vegetation types and outdoor features. Trees appear as circles with species notation, while gardens and lawn areas use specific hatching patterns. Understanding these symbols helps you visualise the completed project and assess the balance between built and natural elements. Site Analysis and Soil Considerations Conducting Proper Site Analysis Professional site analysis forms the foundation of successful site planning. This process involves detailed surveys that measure existing levels, identify soil conditions, assess drainage patterns, and evaluate access requirements. Understanding what is a site plan means recognising that accurate site analysis directly influences design decisions and construction costs. Topographical surveys create contour maps showing natural ground levels across your property. These measurements determine cut and fill requirements, drainage design, and foundation specifications. Steep slopes may require retaining walls or specialised foundation systems, while flat sites might present drainage challenges that need addressing. Soil Testing and Geotechnical Considerations Australian building standards require geotechnical assessment for most residential construction projects. Soil tests determine bearing capacity, reactivity levels, and drainage characteristics that influence foundation design and construction methodology. This information appears on your site plan as soil classification symbols and foundation recommendations. Reactive clay soils, common in many Australian regions, require special attention in site planning. These soils expand and contract with moisture changes, potentially causing structural movement. Your site plan must accommodate these conditions through appropriate foundation design and drainage planning. Drainage and Stormwater Management Planning Effective Drainage Systems Stormwater management represents one of the most critical aspects of site planning, particularly given Australia’s variable rainfall patterns and increasing focus on environmental sustainability. Your site plan must demonstrate how rainwater will be collected, managed, and discharged in compliance with council requirements and environmental best practices. Downpipe locations, shown as small circles or squares on site plans, indicate where roof water is collected and directed to disposal systems. The positioning of downpipes influences both architectural design and landscape planning, requiring coordination between multiple

Read More »
What is cladding? Wooden clad house

What is House Cladding?

When you envision your dream home, the exterior should capture your attention just as much as the interior. House cladding plays a pivotal role in both protecting your investment and creating the aesthetic appeal that makes your property stand out. But what exactly is cladding, and why should it matter to every homeowner? Understanding house cladding empowers you to make informed decisions that impact everything from your energy bills to your property’s market value. Whether you’re building a custom home, renovating, or simply want to understand what protects your home’s structure, this comprehensive guide will equip you with the knowledge needed to choose and maintain the right cladding system. What is Cladding on a House? House cladding functions as your home’s protective outer layer—a non-structural covering system that wraps around exterior walls to create a barrier between your living space and the outside world. Think of cladding as your home’s raincoat, sunhat, and winter jacket combined into one sophisticated protection system. Unlike structural walls that support your roof and floors, cladding focuses exclusively on protection, insulation, and aesthetic enhancement. The cladding material essentially works as an ‘outer skin’ that shields your property while offering tremendous design flexibility. Modern cladding operates on advanced moisture management principles rather than creating an impermeable barrier. The most effective systems allow water vapour to escape from within your home while preventing liquid water from entering, creating a breathing wall system that prevents moisture-related problems like mould growth and timber rot. The Essential Functions of House Cladding Weather Protection and Energy Efficiency Cladding’s primary purpose involves creating a protective barrier for your exterior walls, but its benefits extend far beyond basic weather resistance. Quality cladding systems provide comprehensive protection against driving rain, wind damage, and UV radiation while significantly improving your home’s thermal performance. The insulation properties of modern cladding materials can reduce heating and cooling costs by up to 25% through improved thermal resistance and elimination of thermal bridging. This energy efficiency improvement often justifies premium material investments through ongoing utility savings. Aesthetic Appeal and Property Value Cladding transforms your home’s appearance through virtually unlimited design possibilities. From classic weatherboard charm to contemporary metal finishes, cladding materials offer the flexibility to achieve any architectural style while enhancing curb appeal and property values. Well-selected cladding can increase property values by 10-15% through improved aesthetics, energy performance, and reduced maintenance requirements. The versatility of home design allows customisation that reflects your personal style while complementing your home’s architectural character. Durability and Low Maintenance Quality cladding materials provide long-term protection that minimises ongoing maintenance requirements. Many modern materials require only periodic cleaning and basic upkeep, saving significant time and money compared to traditional exterior finishes that demand frequent repainting or repair. Popular House Cladding Materials Timber and Weatherboard Cladding Timber cladding remains a timeless choice that offers natural beauty and proven performance. Modern treatment technologies have addressed traditional durability concerns while preserving the warmth and character that makes wood perpetually appealing. Australian hardwoods like spotted gum provide exceptional durability and natural weather resistance, while treated softwoods offer cost-effective alternatives. Proper installation and regular maintenance ensure timber cladding performs beautifully for decades. Fibre Cement Cladding Fibre cement represents one of the most significant advances in cladding technology, combining cement, cellulose fibres, and sand to create materials that resist fire, moisture, insects, and UV damage. This engineered material offers exceptional durability with minimal maintenance requirements. Modern fibre cement products feature pre-finished surfaces that maintain appearance for decades without repainting, while installation convenience keeps labour costs reasonable. The material can mimic timber appearance while providing superior weather resistance. Metal Cladding Systems Metal cladding has evolved from basic corrugated steel to sophisticated systems offering exceptional durability and striking modern aesthetics. Aluminium, steel, and zinc each provide unique benefits suitable for different design objectives and environmental conditions. Advanced coating technologies enable metal cladding to withstand coastal salt spray and intense UV exposure while maintaining appearance and protective properties. The material’s reflective properties can significantly reduce cooling loads in hot climates. Stone and Masonry Cladding Natural stone cladding provides unmatched durability and timeless appeal that justifies premium investment for many homeowners. Modern installation systems have eliminated traditional weight and moisture concerns through engineered veneer systems that deliver authentic stone appearance with practical installation convenience. Stone options including sandstone, limestone, and slate each offer distinctive appearances and performance characteristics. Quality stone cladding can perform for 50+ years with minimal maintenance beyond basic cleaning. The Critical Importance of Cladding in Sydney, Australia Cladding holds exceptional significance for any project a Sydney home builder would handle due to the city’s unique combination of coastal climate, urban density, and stringent safety regulations that make proper exterior wall systems essential for both protection and property value. Sydney’s harsh sun exposure, intense summer heat, coastal salt spray, and periodic severe storm conditions create demanding environmental challenges that quality cladding systems address while reducing energy consumption and maintenance requirements. The city’s heightened focus on fire safety following high-profile cladding incidents has resulted in strict combustible cladding regulations and registration requirements that make compliant material selection crucial for insurance coverage, property financing, and legal liability protection. Beyond building compliance, well-designed cladding systems significantly enhance property values in Sydney’s competitive real estate market while providing the thermal performance necessary to manage cooling costs in Australia’s most expensive energy market, making cladding selection a critical investment decision that impacts both immediate comfort and long-term financial returns. Choosing the Right Cladding for Your Home Climate Considerations Australia’s diverse climate zones require careful material selection that matches environmental challenges with appropriate cladding characteristics. Coastal areas demand salt-resistant materials, while bushfire-prone regions need BAL-compliant options that provide adequate fire protection. Understanding your local climate conditions helps narrow material choices to options that will perform optimally in your specific environment while meeting regulatory requirements and insurance considerations. Budget and Lifecycle Value Initial material costs represent only one component of total cladding investment. Installation complexity, maintenance requirements, and durability characteristics significantly impact long-term value, with premium materials often

Read More »
buying home without money

How to buy a house with no money in Australia?

Want to get property without money? Buying a house in Australia without a deposit might seem like a distant dream, especially with rising property prices and the challenge of saving for a substantial down payment. But what if there was a way to turn your dream into reality? Whether you’re a first-time home buyer or someone looking to enter the property market with limited savings or without a hefty upfront sum, there are strategies that can help you secure your own piece of real estate without a hefty deposit. While buying house with no deposit can fast-track your journey to homeownership, however, first you need to understand what it can bring to both side of coins, advantage and disadvantage and be aware if it is right fit for you. Let’s get started with it and diver more into the ways to buy your home sweet home without saving up for deposit. What Does it Mean to Buy a house With No Money? Buying a house with no money typically refers to a scenario where a buyer acquires a property without making a substantial upfront payment or down payment. In most real estate transactions, buyers are required to pay a deposit, usually 10-20% of the property’s value, as an upfront payment to secure a mortgage and demonstrate their financial commitment. While the term “no money” can be somewhat misleading since some costs are inevitable in any real estate transaction, it generally implies that the buyer is not using their own savings or funds to cover the initial purchase expenses. In practice, purchasing a house with no money often involves utilising alternative financing options, creative strategies, or assistance programs to cover the upfront costs traditionally associated with buying a home. You may also like: What is the cheapest way to build a house? What are the Pros and Cons of No-Deposit Home Loans? Buying a home with no deposit can be an attractive option for some prospective homeowners, but it also comes with its own set of advantages and disadvantages. Here are some pros and cons of buying a home with no deposit: PROS CONS You can become a homeowner without having to save up a large sum of money for a down payment. You can bypass the lengthy process of saving for a deposit, which can be particularly challenging for those with limited savings or high living expenses. Owning a home can provide potential long-term financial benefits, such as building equity and securing a valuable asset. You can expedite your entry into the property market, increase your investment property portfolio, allowing you to take advantage of market conditions and potential capital growth. Some lenders offer creative financing solutions for buyers without a deposit, such as guarantor loans or vendor finance, providing more flexibility in terms of financing. Lenders may charge higher interest rates for loans with no deposit, which can result in increased overall borrowing costs over the life of the loan. When borrowing more than 80% of the property’s value, lenders often require borrowers to pay for LMI to protect the lender in case of default, adding to upfront costs. Without a deposit, your choice of lenders and loan products may be restricted, potentially limiting your ability to find a loan with favourable terms. If property values decrease, buying with no deposit home loan can put you at risk of owing more on your mortgage than the property is worth, leading to negative equity. Higher loan amounts and interest rates associated with no-deposit purchases can lead to increased repayment stress, especially if your financial situation changes. If you are looking for house and land packages, we provide a range of options designed to fit your lifestyle and budget. Reach out to us for details! How to Buy a House without Deposit in Australia? Exploring Options 1. Government Programs and Grants The Australian government offers several programs and grants aimed at assisting first-time home buyers, many of which can significantly reduce or eliminate the need for a deposit. A. First Home Owner Grant (FHOG) The First Home Owner Grant (FHOG) is a government initiative designed to assist eligible first-time buyers in purchasing their first home. This grant is a one-time payment, and the amount varies depending on the state or territory where the property is being purchased. The grant offers a lump sum payment that can be utilised to cover part of the deposit or other expenses related to purchasing the property, making homeownership more attainable for first-time buyers. i. Eligibility Criteria You must be a first-time home buyer. The property must be a newly built home, an off-the-plan purchase, a substantially renovated property, or vacant land on which a new home will be built. One applicant must be a permanent resident or an Australian citizen. Applications cannot be made by companies or trusts. ii. Grant Amount and Limits The FHOG can provide a grant of $10,000, depending on the value and type of property. Specific criteria include: The purchase price of the property must not exceed $600,000. If building a new home, the total value of the property, including house and land, must not exceed $750,000. iii. Application Process You can apply for the FHOG either through your lender or directly with the revenue office of the relevant state or territory. Each state or territory has its own specific guidelines and application process, so it’s important to check the requirements based on your location. B. First Home Buyers Assistance Scheme (FHBAS) The First Home Buyers Assistance Scheme (FHBAS) is designed to help eligible first-time home buyers in New South Wales by reducing or eliminating transfer duty costs. Here’s a breakdown of the key details: Eligibility Criteria To qualify for the FHBAS: Purchase a new home, existing home, or vacant land in New South Wales. Ensure that the property’s value falls within the specified thresholds. The purchase should encompass the entire property. Must be individuals and not represent a company or trust. Be at least 18 years old. Neither you nor

Read More »
a good credit score to buy house

What is a good credit score to buy a house in Australia?

Are you aware that your credit score can influence not just your loan approval, but also the affordability of your new home in Australia? It is one of the first thing lenders check when you’re buying your first home. For first time homebuyer or budget-conscious buyers, a good credit score can lead to lower interest rates and more manageable mortgage payments. On average, you need from 500 to 700 credit score to buy a house, but it’s crucial to understand what these scores imply. With a good credit score, you are likely to qualify for better loan terms, lower interest rates, and higher borrowing limits, making homeownership more accessible and affordable. From understanding what constitutes a good versus a bad credit score to exploring strategies to improve your financial standing, we’ll provide the insights you need for a successful home buying experience. Read this blog to learn what credit score you need to aim for and how it can impact your home buying budget. What is a credit score? A credit score or credit rating is a numerical representation of your creditworthiness, which indicates how likely you are to repay debts. It is calculated based on your financial history, including your payment habits, the amount of debt you have, and the length of your credit history. In essence, a credit score helps lenders assess the risk of lending you money or offering you credit. The higher your credit score, the more creditworthy you appear to lenders, which can lead to better loan terms, lower interest rates, and easier approval for credit products like mortgages, car loans, or credit cards. Credit scores typically range from 0 to 1200, depending on the credit reporting agency, with higher scores indicating better credit health. There are three main credit reporting agencies in Australia—Equifax, Experian, and illion. Each of these credit bureaus calculates credit scores using slightly different methods, but all of them follow the same general range of 0 to 1200. How is a credit score calculated? Credit scores are calculated based on various factors that reflect your financial behaviour and history. Here’s a breakdown of how your credit score is typically calculated: Payment History (30-35%): This is the most important factor. It looks at whether you’ve paid your bills on time, including credit card payments, loans, and utility bills. Late or missed payments can significantly lower your score. Credit Utilisation Ratio (20-30%): This measures how much of your available credit you’re using. For example, if you have a credit card limit of $10,000, and you’ve used $3,000, your utilisation ratio is 30%. Keeping this ratio below 30% is generally considered good for your score. Length of Credit History (10-15%): The length of time you’ve been using credit also affects your score. A longer history of credit can boost your score, as it gives lenders more information about your long-term financial habits. Types of Credit (10%): This factor considers the different types of credit you have, such as credit cards, mortgages, personal loans, and auto loans. A mix of different types of credit can positively impact your score, as it shows you can manage various forms of credit responsibly. New Credit Inquiries (5-10%): Every time you apply for new credit, a credit inquiry is made, which gets recorded on your credit report. Too many inquiries in a short period can lower your credit score, as it may indicate that you’re taking on too much debt or are in financial distress. Total Debt (5-10%): The total amount of debt you owe across all credit accounts is also considered. Higher levels of debt can negatively impact your score, especially if your debt-to-income ratio is high. Negative Information: Factors like bankruptcies, defaults, and court judgements can drastically reduce your credit score. This negative information can stay on your credit report for several years, making it harder to improve your score during that time. Want a stress-free home building experience? Whether you are looking for ground up build or knockdown rebuild, from initial design to final touches, we make it seamless and enjoyable. Book a consultation to know how we do it. What is a good credit score needed to buy a house? In Australia, a credit score range between 500 and 700 is considered average. This range may still allow you to qualify for a mortgage, but you might face higher interest rates and less favourable terms. However, 620 is often considered a minimum credit score for most conventional loan. A credit score above 700 is regarded as very good, and above 800 is considered excellent. With a score in this range, you’re more likely to receive competitive interest rates and favourable loan terms, making it easier to secure a mortgage with better conditions. How much can I borrow with different credit score? The amount you can borrow for a home loan can vary significantly based on your credit score, among other factors like: Income and Debt-to-Income Ratio: Your income and debt-to-income ratio are critical in determining how much you can borrow. Higher income and lower debt levels generally allow for larger loan amounts. Down Payment: A larger down payment can improve your borrowing capacity and reduce the impact of a lower credit score. Lender Policies: Different lenders have varying criteria, so the exact amount you can borrow may differ based on their specific requirements. Also Read: How much deposit do I need to buy house in 2024? Can I buy a home with a bad credit score in Australia? A credit score below 500 is generally considered poor. A low credit score can significantly impact your ability to secure a home loan on standard terms. However, it doesn’t necessarily mean you can’t buy a house at all. Options for Buyers with Bad Credit: Specialist lenders: These lenders cater to borrowers with less-than-perfect credit. While they often have higher interest rates, they offer opportunities for those with a poor credit score. Guarantor loans: If you have a family member or friend with good credit, they might be willing to guarantee the loan, improving your chances of approval.

Read More »
Pre-settlement inspection

Pre-Settlement Inspection Checklist: Homebuyers Must know

You’ve found the perfect home, the offer has been accepted, and settlement day is approaching. Before the keys officially become yours, it’s crucial to conduct a pre-settlement inspection. This final walkthrough is your last opportunity to catch any potential issues, verify that agreed-upon repairs have been completed, and ensure the property is in the same condition as when you first saw it. As part of the sale, it’s crucial to organise a thorough inspection, verifying against accurate inspection reports to ensure that everything is in order. Every part of the property, from the interior and exterior to the structural and documentation, needs to be first inspected to make sure that any special conditions are fulfilled. If there is any damage, ask the vendor to fix it before settlement. In this blog, we have provided you the checklist which not only protects your investment but also provides peace of mind, ensuring that your new home is ready for a smooth transition. What is a Pre-Settlement Inspection? A pre-settlement inspection, also known as a final walkthrough, is a crucial step in the home-buying process that occurs just before the settlement date. This inspection lets home buyers confirm that the condition of the property is the same as mentioned in the sales contract. It is the buyer’s final chance to verify that all repairs have been finished, all fixtures and appliances are present and functional, and that the property has not suffered any new damage since the first viewing. While house inspection is not mandatory, it is highly recommended to protect your investment. Buyers should do the inspection themselves, along with a witness, such as the real estate agent. They should schedule the appointment in advance at a time that suits the vendor. To make sure the vendor is prepared for the final inspection, you must give them a fair amount of warning. As an alternative, you might ask the real estate agent to set up a time that works for everyone. If it’s a private transaction, you can make these arrangements with the vendor directly. When should you do the pre-settlement inspection? The pre-settlement inspection should ideally be conducted a few days or a week before settlement date, typically within five to seven days. This timing allows enough room for any last-minute issues to be resolved without delaying the settlement process. Conducting the inspection too early might mean some final repairs or cleaning haven’t been completed, while doing it too late might not leave enough time to address any discovered issues. Importance of inspecting the property The pre-settlement inspection is crucial for several reasons: Verification of Condition: It ensures that the property is in the condition promised by the seller. Any discrepancies can be addressed before the sale is finalised. Confirmation of Repairs: It allows the buyer to confirm that any agreed-upon repairs or modifications have been completed to a satisfactory standard. Functionality Check: It gives the buyer the opportunity to test all appliances, fixtures, and systems to ensure they are working correctly. Avoiding Surprises: It helps prevent any unwelcome surprises after moving in, such as undisclosed damage or missing fixtures. Negotiation Leverage: If issues are found, the buyer can negotiate with the seller for repairs or financial compensation before the final settlement. Looking for a complete home building solution? With our turnkey service, you’ll have a dedicated team, ensuring that each phase of your project runs smoothly and efficiently. Contact us today. Pre-Settlement Inspection Checklist for Your New Home As you approach the final stages of your home buying journey, this inspection ensures that the property is in the agreed-upon condition before you take ownership. Here’s a checklist divided into categories to guide you through this important process. Interior Inspection: 1. Verify Agreed Repairs and Inclusions Ensure all repairs specified in the contract have been completed to your satisfaction. Check that all included items (appliances, fixtures, etc.) are present and in working order. 2. Check Plumbing Turn on all faucets and showers to check for water pressure and leaks. Flush all toilets to ensure they work properly. Make sure the water heater is functioning and there are no leaks. 3. Test Electrical Systems Test all electrical outlets and light switches to ensure they are operational. Turn on all lights to check for functionality. Inspect the fuse box or circuit breaker panel for any signs of damage or wear. 4. Evaluate Appliances Test the stove, oven, refrigerator, dishwasher, and microwave to ensure they work. If included, test the washer and dryer. 5. Assess Heating and Cooling Systems Turn on the heating and cooling systems to verify they are working correctly. Check and replace filters if necessary. 6. Review Doors and Windows Check for smooth operation by opening and closing all doors and windows. Ensure all locks and latches are functional. Inspect for any cracks or damage. 7. Confirm Cleanliness and General Condition The interior property should be clean and free of rubbish. Inspect carpets, tiles, and other flooring materials for stains or damage. Check for any marks, stains, or damage on walls and surfaces. Exterior Inspection: Examine the property’s exterior for damage to siding, roofing, or windows. Check gutters, downspouts, and drainage systems. Inspect the driveway, and walkways. Verify the condition of fences, gates, and outdoor structures. Examine landscaping, including trees, shrubs, and lawns. Check the pool and spa filters to ensure they are clean and operational. Structural Inspection: Look for any cracks, leaks, or signs of water damage on walls, ceilings, and floors. Check for any visible issues that could indicate foundational problems. Inspect for signs of water damage, mould, or pests on attic and basement. Ensure there are no sagging beams or other signs of roof structural damage. Check for cracks, leaks, or other signs of wear and tear on chimney. Documentation: Double-check that all agreed-upon repairs have been completed. Ensure that utilities are in working order and transferred to your name. Bring a copy of the contract of sale. Have a checklist or camera to document findings. Should

Read More »
Home Buying Deposit

How much deposit do I need to buy house in 2024?

With property prices continuing to rise in many areas, it’s natural to wonder just how much you need to save or how much deposit you need to buy a home. This is always the first question almost every home buyer thinks of. The answer can vary depending on several factors, but understanding the basics can set you on the right path. In most cases, the average deposit for a house ranges between 5% and 20% of the total purchase price. Yet, there’s more to consider than just the deposit amount. Factors like lender requirements, first-home buyer programs, and personal savings plans can all impact your home-buying journey. Read this article, and find the answer to your question and gain the confidence you need to purchase your first home. Understanding the Deposit Requirement A deposit, also known as a down payment, is the initial amount you pay upfront when purchasing a house. Usually, it is stated as a percentage of the price paid when buying the property. The deposit serves as a sign of your commitment to the purchase and is essential for securing a mortgage from a home loan lender. Paying a larger deposit can help reduce your monthly mortgage payments and may allow you to secure better loan terms. How much deposit do I need to buy a home? The standard deposit percentage varies depending on the lender’s requirements. However, common benchmarks include: A 20% deposit is frequently considered optimal when purchasing a home. It gives you access to the most reasonable mortgage rates and helps you avoid paying lenders mortgage insurance. This larger deposit tells lenders that you are financially reliable, which can lead to better loan terms. A 10% deposit is also typical and provides a wider selection of mortgage alternatives at lower interest rates than a smaller deposit. It creates a balance between affordability and favourable credit terms. A 5% deposit is the minimum some lenders will accept, but it usually comes with higher interest rates and stricter lending criteria. This lower deposit can limit your mortgage options and may result in higher overall costs. Also Read: Can International Students Buy a House in Australia? Does the source of your deposit matter? Absolutely, the source of your home loan deposit is important. Lenders are becoming more demanding about where your deposit originates from. This is mostly intended to analyse your overall financial soundness. Whether your deposit comes from personal savings, a gift, the sale of assets, or an inheritance, each source can have an impact on how lenders assess your financial health and ability to home loan repayment capability. Clearly stating the origin of your home deposit is critical, as utilising funds from secret loans or unlawful sources might jeopardise your mortgage application while possibly resulting in legal consequences. Other costs of buying a house Transfer Duty or Stamp Duty: Calculated based on the home’s value. Legal/Conveyancing Fees: Costs for legal services or conveyancing. Lenders’ Mortgage Insurance (LMI): Required if you borrow more than 80% of the purchase price. Registration of Title: Fees for transferring property ownership. Mortgage Registration Fees: Fees to register the mortgage with authorities. Home Loan Application Fees: Includes charges for independent property valuations. Reports: Fees for pest, building, or strata inspections. Also Read: How much does it cost to build a house in Australia? Own your dream home sooner with our home and land packages. Choose from our range of single or double-storey home and land packages. Contact us for more information. Factors Influencing Deposit Amount Property Value: The property value has a considerable impact on the deposit amount. Higher-value properties necessitate greater deposits. To precisely figure out the deposit required, you must first understand the property market in the area of interest. Lenders Mortgage Insurance (LMI): LMI applies to buyers who cannot pay a 20% deposit. LMI protects the lender in the event that the borrower fails on the loan. However, it incurs an additional expense for the customer. The insurance premium can be paid upfront or added to the home loan amount, raising the total repayment cost. Government Schemes and Grants: Many governments provide schemes and grants to help first-time homeowners. These can greatly lower the deposit amount needed. For example, Australia’s first property loan scheme allows qualifying first-time buyers to buy a property with as little down payment without paying LMI. Market Conditions: Market conditions also influence deposit requirements. In a seller’s market, where demand exceeds supply, purchasers may need to provide bigger deposits to make their offers more competitive. In contrast, in a buyer’s market where supply exceeds demand, deposit amounts may be more flexible. What if I have a smaller deposit? 1. Higher Loan-to-Value Ratio (LVR) A smaller deposit results in a higher Loan-to-Value Ratio (LVR). LVR is the ratio of your loan amount to the property’s value. For example, with a 5% deposit on a $500,000 house, the loan amount would be $475,000, resulting in a 95% LVR. This higher ratio poses more risk for lenders and often leads to stricter lending criteria and additional costs for the borrower. 2. Lender’s Mortgage Insurance When your deposit is less than 20% of the property’s value, you will likely need to pay LMI. LMI is an insurance policy that protects the lender if you default on the loan. This insurance can add thousands of dollars to your home purchase cost. Example: If the LMI is AUD 11,875, this amount is typically added to your mortgage, increasing the total loan amount you borrow. Thus, if your home loan is AUD 475,000 and the LMI is added, your total loan amount would be AUD 486,875. 3. Higher Interest Rates Home Loans with low deposits usually have higher interest rates. Lenders charge these rates to compensate for the higher risk that comes with high LVR loans. Even a modest increase in interest rate can have a substantial impact on the loan’s overall cost over its life. For example, an extra 0.5% interest on a $475,000 loan can result in thousands of dollars in extra instalments

Read More »
cheapest way to build a house

What is the cheapest way to build a house?

Building a dream home often seems like a distant fantasy reserved for those with deep pockets and endless budgets. But what if I told you that creating a beautiful, comfortable, and functional home doesn’t have to break the bank? With a bit of creativity, strategic planning, and resourcefulness, you can construct a custom house that not only meets your needs but also fits within a reasonable budget. However, did you know? While there are various cost-effective ways to build a home, from choosing a simple floor plan to building in phases, it’s equally important to consider the different affordable styles of homes available. After all, there are the cheapest styles to build, acting as a blank canvas for your personal touches. So, let’s first explore the cheapest types of homes to build and then dive into the different affordable ways to build your favourite style of home in the most economical way. What Home Styles Are Cheapest to Build? Tiny House: Tiny house, typically under 400 square feet, offer an affordable and efficient living solution. Their compact size reduces construction and material costs, while their design emphasises simplicity and functionality. And the foundation can cost on an average between $5.50 and $8 per square foot. Ideal for those looking to downsize or minimise expenses, tiny homes are also energy-efficient, resulting in lower utility bills. Modular Homes: Modular homes are pre-fab in sections and assembled on-site, offering a cost-effective alternative to traditional construction. Their factory-built components help lower costs and speed up construction. These homes can be customised to suit various needs and preferences, providing a balance between affordability and personalisation. It can cost in between $80 to $160 per square foot. Prefabricated Homes: Prefabricated homes are partially or fully constructed in a factory before being transported to the site. They offer affordability through bulk material purchasing and streamlined construction. With various styles available, prefab homes are a flexible and cost-effective choice. Container Homes: Shipping container homes utilise repurposed shipping containers, providing a durable and eco-friendly option. They can be combined and customised to create unique living spaces. While initial costs can be low, additional investments in insulation and interior finishing may be needed to enhance comfort. The cost to build a custom container home on an average is $250 to $400 per square foot. A-Frame Homes: A-frame homes feature a distinctive triangular shape with a roof that extends to the ground. Their simple design reduces construction complexity and costs. Known for their natural light and open interior spaces, A-frame homes are the cheapest option, especially for vacation or weekend retreats. Log Cabins: Log cabins, constructed from logs, offer a rustic and durable home option. The use of natural materials can lower costs if logs are sourced locally. While log cabins provide excellent insulation and a unique aesthetic, they require more maintenance compared to other home types. Built-in-Kit Homes: Kit homes come with pre-cut materials and assembly instructions, making them a practical and affordable option. Easy to build, they can be assembled with minimal professional help. The average cost to build kit-homes comes around $80 to $150 per square metre, offering flexibility, and making them suitable for those who are comfortable with DIY projects. Also Read: Australian Standards for Building and Construction A custom-built home by Dhursan Construction is an investment that will bring you joy for years to come. With our experienced home builder, design the perfect space for you and your family. Contact us today. Cheapest Ways to Build a House Opt for a Smaller Design Choosing a smaller design for your house is not only a practical decision but also a financial one. It’s like trimming excess financial fat, allowing you to reduce overall construction costs, lower utility bills, and decrease maintenance expenses. Moreover, maintenance expenses are typically more manageable in a smaller space. Just as a well-tailored suit flatters your figure and highlights your best features, a smaller home focuses on what truly matters. It helps to maximise space by incorporating multipurpose rooms and efficient storage solutions, making every square foot count. Prioritise your needs and desires to ensure functionality is maintained. Choose Simple Floor Plans Opting for a simple floor plan can save you both time and money during the building process. It’s like taking the most direct and efficient route to affordability. By reducing the square footage with the square or rectangular floor plan, you can avoid unnecessary corners and complex angles, ultimately minimising material waste and lowering labour costs. Simplicity in the design also often leads to quicker construction, as there are fewer complexities to navigate. However, it’s essential to work with an architect or designer who can help create a functional floor plan that optimises space and avoids any wasted areas. They can ensure that the layout is practical and suits your specific needs while maintaining a straightforward and cost-effective design. Use Cost-Effective Materials Going for cost-effective materials is an excellent strategy to minimise the cost of building your house. For example, prefab panels, bamboo, or concrete blocks can be more budget-friendly than traditional materials like brick or wood. These alternative materials can often be sourced at lower costs and offer comparable durability and insulation properties. However, it’s crucial to research and evaluate the specific characteristics of each material to ensure they meet your needs. Consider factors such as durability, resistance to weather conditions, and energy efficiency. By carefully selecting cost-effective materials, you can achieve both affordability and quality in your home construction. Consider Modular or Prefabricated Homes Opting for a modular or prefab home is like unlocking the benefits of controlled and streamlined construction. These types of homes are built in a factory or controlled environment and are usually more energy-efficient, providing long-term savings. First, the construction process is typically faster and more efficient, leading to fewer delays and associated costs. Second, the controlled environment allows for better quality control, as the construction is not affected by adverse weather conditions. Third, modular homes are often more energy-efficient, as they are designed and

Read More »
can international student buy a house in Australia

Can International Students Buy a House in Australia?

Owning property in Australia is the dream of every international student, a symbol of stability, security, and a lasting connection to this vibrant land. Many students often gravitate towards vibrant urban centres and student-friendly neighbourhoods such as Melbourne, Sydney, Brisbane, and Perth, cities that not only offer prestigious universities but ample job opportunities. Due to visa restrictions, buying a home while studying presents a unique set of challenges and limitations in accessing favourable financing options. However, international students can purchase a house in Australia even if they don’t have full access to funds upfront by applying for a home loan. In this blog, we will explore how, as international students, you can navigate the financial options, costs associated with purchasing property and fulfil your aspirations of property ownership in Australia. Can an International Student Get a Home Loan in Australia? In Australia, specific lenders may offer home loans to international students on specific visa types, allowing them to borrow up to 80% of the property’s purchase price if they meet the lender’s criteria. It’s important to note that eligibility requirements and loan terms vary among lenders. Therefore, it’s advisable to explore different options and seek guidance from mortgage brokers or financial institutions specialising in loans for international students. What type of property can international students buy? International students in Australia are generally restricted from buying existing residential properties due to government regulations. However, they can typically purchase new properties or vacant land with the intent to build, subject to certain conditions: New Properties: International students can buy newly built residential properties directly from developers or through the resale market if they have not been previously occupied. Vacant Land: Students can purchase vacant land with approval to build a new dwelling, provided they meet all local council and planning requirements. International students are typically prohibited from buying existing residential properties, including established homes or apartments that have been previously lived in. These restrictions are in place to prioritise housing availability and affordability for Australian residents. Looking to build your dream home from the ground up and personalise it to your exact specifications? With our strong suit in custom build home we work closely with you to bring your dream visions to life. Book a consultation today. Also Read: Top 10 Cheapest Coastal Towns to Live in Australia Requirements for International Students to Buy a House in Australia International students with temporary resident visas considering purchasing property in Australia must meet several specific requirements and adhere to various regulations. Here’s a comprehensive guide to the essential requirements: Have Eligible Student Visas To begin with, it’s essential to understand which visas allow for the purchase of property. International students on the following visas can buy property in Australia: Temporary Graduate Visa (subclass 485): This visa allows holder to live, study, and work in Australia temporarily after completing their studies, providing an opportunity to gain practical work experience. Student Visa (subclass 500): This visa permits international students to stay in Australia while they undertake full-time study in a registered course at an educational institution. Skilled-Recognised Graduate Visa (subclass 476): This visa is for recent engineering graduates of recognised institutions and allows the holder to live, work, or study in Australia for up to 18 months. Get Foreign Investment Review Board (FIRB) Approval One of the most critical steps for international students is obtaining approval first from the Foreign Investment Review Board (FIRB). This is mandatory for non-residents and temporary visa holders. Application Process: Before purchasing the property, you must apply for FIRB approval. The application can be submitted online through the FIRB website. Fees: The application incurs a fee, which varies depending on the property value. Criteria: FIRB approval is typically granted for new properties, vacant land, or established dwellings to be redeveloped. Purchasing an established dwelling solely as an investment property is generally not allowed. Request Financing and Home Loans Securing a home loan as an international student can be challenging, but it is possible with the proper preparation and understanding of lender requirements. Lender Policies: Not all banks or financial institutions offer home loans to international students. Research and find lenders that provide specific loan products for non-residents. Deposit Requirements: International students usually need a higher deposit than Australian citizens. Typically, a 20% deposit of the property value is required, with 5% for additional costs like stamp duty. Proof of Income: Students must demonstrate their ability to repay the loan. This includes providing evidence of income, such as part-time work, scholarships, or financial support from family. Interest Rates: Expect higher interest rates compared to those offered to Australian citizens or permanent residents. Have a Good Credit History A credit score is a numerical measure of a person’s creditworthiness. It assesses how likely someone is to repay their debts and meet their financial obligations. Lenders, such as banks and financial institutions, use credit ratings to determine the risk of lending money to a specific individual. Why a Good Credit History Matters for International Students Buying Property in Australia? When it comes to securing a home loan in Australia as an international student, a good credit history plays a crucial role. Here’s why: 1. Loan Approval: Lenders assess your credit history to determine the risk involved in lending you money. A good credit history demonstrates consistent and timely repayments of past debts, including credit cards or personal loans. This track record increases your chances of loan approval. 2. Interest Rates: Besides loan approval, your credit score directly influences the interest rate offered on your home loan. A good credit history signifies a lower risk for the lender. This translates into lower interest rates, saving you a significant amount of money over the life of your loan. 3. Loan Amount: In some cases, lenders might limit the loan amount offered to borrowers with poor credit history. A lower loan amount might restrict your purchasing power, potentially limiting your property options. Don’t settle for a rental; own your own space! We will provide expert guidance

Read More »

Enquiry For Hamptons Style: The Ultimate Guide!

One of our agents will contact you soon!

Blank Form (#6)

Enquiry For Hamptons Style: The Ultimate Guide!

One of our agents will contact you soon!

Contact Us Form